Dow Surges 3.03%, VIX Sinks to 16.61: Closing Notes for Wednesday
Wednesday, November 4, 2026: stocks rallied hard the day after Democrats won both chambers of Congress. The Dow rose more than 3%, which The Motley Fool called the biggest post-midterm rally in 44 years, while oil fell more than 8% and the VIX lost about a fifth of its value. Nvidia and the data center trade went the other way, and after the bell, guidance split the earnings reports sharply.
How the session closed
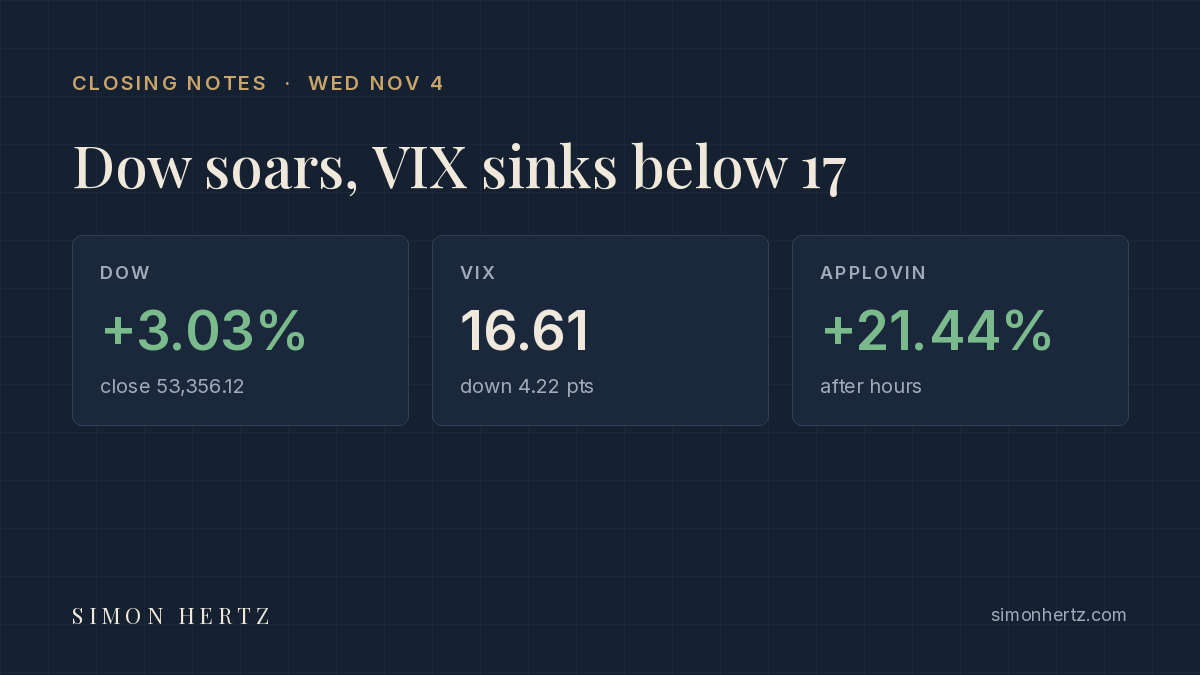
- Indexes. The Dow closed at 53,356.12, up 1,569.40 points or 3.03%. The S&P 500 rose 119.70 points, or 1.58%, to 7,688.62. The Nasdaq Composite added 364.50 points, or 1.44%, to 25,736.51. The Russell 2000 gained 44.50 points, or 1.58%, to 2,856.95 (CNBC quote pages; TheStreet and The Motley Fool agree on the moves).
- Why. Traders read the election result together with a drop in oil tied to hopes for an end to the Iran war (TheStreet, OilPrice.com). AI data center names lagged on concern about the Democratic wins, including the Texas governor’s race (StockTitan).
- Big names. Microsoft rose 6.68% to $555.80 and Amazon 6.12% to $266.03, while Nvidia fell 3.17% to $200.13 (CNBC). We could not confirm a specific catalyst for the Microsoft and Amazon moves.
- Other closes. McDonald’s rose 6.53% to $280.22 after adjusted EPS of $3.57 beat $3.38. CVS fell 12.53% to $79.96 after outlining a split into two companies by the first half of 2028 (CNBC; The Motley Fool).
- Midday moves. StockTitan’s quote data near 1:01 p.m. ET showed Duolingo up 34.13% and Kyndryl up 35.24%, with Amdocs down 26.67%, FIS down 24.16%, Datadog down 13.94% and CoreWeave down 9.01%. These are midday figures, not closes.
- Sectors. Energy fell the most, tech and industrials also lost ground, and nearly everything else rose (TheStreet). Consumer staples hit a record high around midday (StockTitan).
- VIX. 16.61, down 4.22 points or 20.26%, last at 4:15 p.m. ET (CNBC). That matches Tuesday’s published 20.83 close.
- Yields. At 5:05 p.m. ET the 2-year was at 4.581%, down 0.033 on CNBC’s measure; the 10-year at 4.888%, down 0.062; and the 30-year at 5.276%, down 0.048. Those changes run from CNBC’s own prior close. Against the 5:05 p.m. readings we published Tuesday, the 10-year is 0.078 lower, close to Trading Economics’ drop of about 0.08.
- Fed pricing. Trading Economics put the odds of a 25-basis-point December hike near 77%, down from 84% a week ago.
- Oil. WTI was at $88.04, down $8.05 or 8.38%, at 4:59 p.m. ET (CNBC). Brent was at $94.67, down $8.93 or 8.62%; CNBC’s stamp reads 11:09 p.m. BST, a label that doesn’t fit November, but Trading Economics’ $94.68 agrees. Both are last quotes, not official settlements. The White House tied Tuesday’s losses to the war, and President Trump said no strike on Iran was immediately planned (OilPrice.com).
- Data. ADP showed 86,000 private jobs in October, above the 75,000 Dow Jones estimate (CNBC via StockTitan). The September trade deficit was $105.0 billion, down from $105.7 billion (BEA, via the market wraps below). ISM services slipped to 54.5 from 54.9, against a 54.8 forecast; new orders fell to 55.9 from 59.8, employment rose to 51.4 from 50.1, and prices eased to 73 from 74 (ISM, Trading Economics).
- Treasury. The refunding left coupon and floating-rate auction sizes unchanged for the next several quarters and moved the 7-year note to a quarterly new-issue format with two reopenings (Trading Economics).
After hours
Quotes below are CNBC’s, read between 5:19 and 5:23 p.m. ET, compared with the 4:00 p.m. close.
- AppLovin. Up 21.44% to $330.00. EPS of $4.30 beat $4.04, revenue of $2.18 billion beat $2.08 billion, and fourth-quarter revenue guidance of $2.37–$2.40 billion topped $2.25 billion (Investing.com).
- Coherent. Up 7.75% to $210.21. Adjusted EPS of $2.09 beat $2.02, and the guidance midpoint of $2.38 a share compares with $2.24 expected (Investing.com).
- Qualcomm. Down 7.96% to $159.41. EPS of $2.17 was in line. Revenue beat, though sources differ on the figure: Investing.com has $10.44 billion against $10.14 billion, and Finwire has $10.32 billion. Investing.com cited the forward outlook and handset weakness; the EPS guidance midpoint of $2.25 compares with $2.27 expected.
- Arm. Down 0.42% to $191.00; Grafa had the shares off about 2% earlier. Revenue of $1.44 billion beat $1.38 billion, and adjusted EPS of $0.52 beat $0.47, but royalties of $670 million missed $720.8 million (Grafa, citing LSEG). Third-quarter revenue guidance is about $1.54 billion, against $1.53 billion expected.
- Dutch Bros. Down 18.50% to $35.85 after full-year revenue of about $2.1 billion trailed a $2.131 billion consensus (Investing.com).
- Zillow. Down 14.68% to $29.39. EPS of $0.55 missed $0.59, and fourth-quarter revenue guidance of $635–$665 million trailed $708.6 million (Investing.com).
- HubSpot. Down 10.45% to $194.00. The quarter beat, but fourth-quarter EPS guidance of $3.85–$3.87 trailed $4.09 (Investing.com).
- Snap. Down 9.97% to $5.33. Revenue of $1.72 billion just missed $1.73 billion (Investing.com).
- Expedia. Down 9.46% to $286.00, even with revenue up 12% to $4.94 billion, adjusted EPS of $9.39 and raised full-year guidance. Fourth-quarter gross bookings growth is guided at 3.3–5.2%, well below the 11% just reported (company release). We could not confirm the consensus or a stated reason for the drop.
What it means for options traders
Right on the move, hurt by the vol. Reuters, citing ORATS, reported on Tuesday that options priced about 0.8% for today, and Tuesday’s 20.83 VIX works out to about 1.30% a day on the divide-by-16 shortcut. The S&P 500 moved 1.58%, more than either figure, and the VIX still fell 4.22 points. Realized came in above implied, yet implied collapsed once the unknown was gone. A rally also tends to pull index vol lower, so both forces pointed the same way.
Dispersion under the index. The Dow rose 3.03% with Nvidia down 3.17%, and that gap sits inside a single headline number. Tonight’s reports widen it: Benzinga had 16.52% implied for AppLovin, 8.33% for Qualcomm and 12.57% for Snap this morning, against after-hours moves of 21.44%, 7.96% and 9.97%. One report ran past what was priced, and two stayed inside it. We could not confirm a closing skew reading.
What is left on the curve. A 16.61 VIX implies about 1.04% a day. With the election gone, the next scheduled events are Thursday’s jobless claims, Friday’s payrolls (consensus 65,000 after 29,000) and next Tuesday’s October CPI (Trading Economics). Calendar spreads now compare a front month that has lost its largest event with expirations that still hold those dates. For the names that reported tonight, front-month event premium usually gets repriced at the next open, so setting the actual move against the implied one is the useful exercise.
Sources
- CNBC quotes: Nasdaq, Dow, Russell 2000, VIX, 2-year, 10-year, 30-year, WTI, Brent; stocks MSFT, AMZN, NVDA, MCD, CVS; after-hours APP, COHR, QCOM, ARM, BROS, ZG, HUBS, SNAP, EXPE.
- TheStreet, Stock Market Today (Nov. 4, 2026) (closing moves, sectors, oil).
- The Motley Fool, Stock Market Today, Nov. 4 (closes, McDonald’s, CVS).
- StockTitan, Stock Market Today Live, November 4, 2026 (midday movers, ADP, data center names).
- Investing.com, After-Hours Movers (results, consensus, reasons).
- Finwire, Qualcomm (differing revenue figure).
- Grafa, Arm Q2 2027 revenue and Breaking The News, Arm.
- Expedia Group third quarter 2026 release, SEC filing.
- OilPrice.com, Oil Crashes 9% (oil, reasons).
- Trading Economics, United States Government Bond Yield (yields, refunding, Fed pricing).
- Trading Economics, Brent.
- ISM, October 2026 Services PMI Report and Trading Economics, ISM Services PMI (forecast).
- This morning’s Desk Notes (Reuters/ORATS implied move, Benzinga implied earnings moves, payrolls consensus, CPI date, all read this morning).
- Not confirmed and left out: a closing MOVE reading, closing sector percentages, a closing skew reading, official oil settlements (prices above are last quotes), today’s bill auction results, Fed remarks, closing moves for the midday names above, Apple’s close, Trump Media (sources disagreed), gold (sources disagreed), and Reuters’ and AP’s wraps, which would not load.
- These closing notes are an AI-written digest grounded in the named sources above. Figures may be revised; check primary sources before relying on any number.
Related reading
- Trading Calendars by Simon Hertz, available on Amazon.
- Trading Butterflies by Simon Hertz, available on Amazon.
- Trading 0DTE Spreads by Simon Hertz, available on Amazon.
- All titles: Simon Hertz author page on Amazon.
This post is for education only. It is not investment advice or a recommendation to buy or sell any security or option. Options involve risk and are not suitable for all investors. Figures are from the sources listed and may be revised; check primary sources before relying on any number.