Nasdaq Futures Climb on Nvidia's Beat; FOMC Minutes and a 20-Year Auction Ahead: Desk Notes for Wednesday
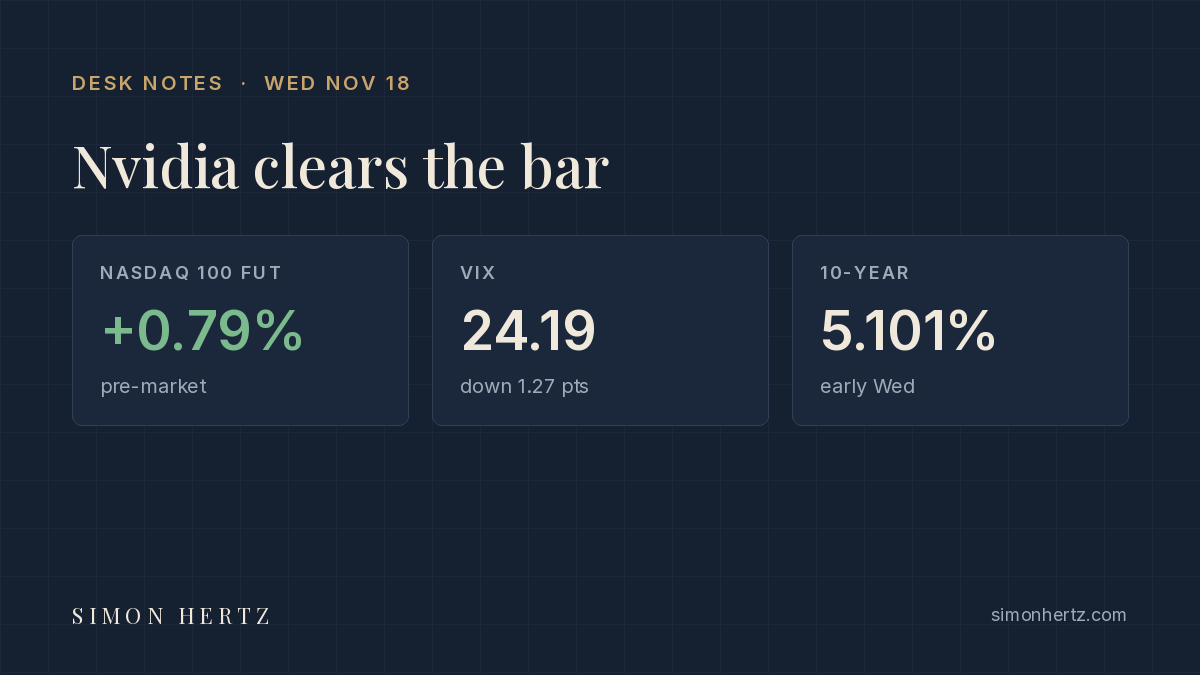
Wednesday, November 18, 2026: the report the market waited on all week is out, and futures are leaning higher on it. At 7:07 a.m. ET, Nasdaq 100 futures were at 27,288.75, up 213.25 points or 0.79%; S&P 500 futures were at 7,381.25, up 22.25 or 0.30%; and Dow futures were at 50,802, down 13 or 0.03% (CNBC). Nvidia beat expectations and gave a solid outlook in its first results since its CEO’s exit (CNBC), and the rest of the day turns to rates: housing data at 8:30 a.m., a 20-year bond auction at 1:00 p.m. and the minutes of the last Fed meeting at 2:00 p.m. ET. On Tuesday the S&P 500 and Nasdaq closed lower as an early chip rebound faded (CNBC).
Before the bell
- Futures. The CNBC readings above are measured against the prior settle. Tech carries the gain while the Dow is flat.
- Nvidia. Shares were at $160.34 in pre-market trading at 7:17 a.m. ET, up $4.88 or 3.14% from Tuesday’s close of $155.46 (CNBC). The company reported another earnings beat and a strong revenue outlook, while a Wall Street Journal report that the SEC is investigating the company, along with the fallout from the leadership change, stays in the background (CNBC).
- Chips and AI names. Semiconductor stocks rose before the open on the results, with the iShares and VanEck semiconductor ETFs up around 2.8% earlier this morning, and AI cloud providers such as CoreWeave and Nebius gaining more (CNBC). Asian chip suppliers rallied overnight, and South Korea’s Kospi rose 2% (CNBC).
- Trade talks. President Trump has arrived in Shenzhen for the APEC summit, with talks with China’s Xi Jinping and Russia’s Vladimir Putin set for Thursday; trade and limits on advanced AI chips are in focus (CNBC).
- VIX. 24.19, down 1.27 points, at 7:17 a.m. ET (CNBC).
- Yields. At about 7:17 a.m. ET the 10-year Treasury yielded 5.101%, down 0.002 point; the 2-year 4.802%, up 0.013; and the 30-year 5.448%, down 0.011 (CNBC).
- Oil and gold. WTI crude was $85.18 a barrel, down $0.83 or 0.97%, at 7:08 a.m. ET (CNBC). Gold futures were at $3,772.50, down 2.37%, as expectations of a Fed rate increase next month pulled money away from assets that pay no interest (CNBC).
On today’s calendar
- Before the open: Lowe’s, Target and TJX report (Yahoo Finance).
- 8:30 a.m. ET: October housing starts, consensus 1.27 million after 1.221 million; building permits, consensus 1.38 million after 1.398 million (Trading Economics).
- 10:00 a.m. ET: October pending home sales, consensus -2% after -7.3% (Trading Economics).
- 10:30 a.m. ET: weekly EIA crude inventories, consensus a build of 0.4 million barrels after 4.657 million (Trading Economics).
- 1:00 p.m. ET: 20-year bond auction; the last one sold at 5.469% (Trading Economics).
- 1:35 p.m. ET: Fed official Barr speaks; 2:00 p.m.: minutes of the last FOMC meeting; 2:30 p.m.: New York Fed President Williams (Trading Economics).
- After the close: Palo Alto Networks reports (Yahoo Finance).
What it means for options traders
The earnings crush. Nvidia options that carried the earnings premium into Tuesday’s close usually lose much of that implied volatility at the open the morning after, whatever the direction. A long straddle can be right on direction and still lose if the move comes in smaller than what was priced; a short premium position can see a quick gain from the drop in implied vol even as the stock moves. Because Nvidia is so heavily weighted, some of that reset shows up in Nasdaq 100 options too.
What a 24.19 VIX prices. Dividing by 16 gives about 1.51% a day, or roughly 112 points on S&P 500 futures at this morning’s level. It is a rule of thumb, not a forecast. The VIX is lower this morning but still well above where it began the month, so index protection remains expensive even with the biggest single-stock event of the week behind us.
From earnings risk to rate risk. With the 10-year above 5.1%, the afternoon matters: the 20-year auction at 1:00 p.m. and the FOMC minutes at 2:00 p.m. can move yields, and yields have been pulling equity volatility around. That is a different kind of event from an earnings report. It lands mid-session, its effect on the index is less direct, and it often shows up first in the bond market. Calendar spreads are one way traders think about this: the front expiration holds the near-term event, the back month holds the longer view, and the trade depends on how the gap between the two moves.
0DTE conditions today. Wednesday expirations carry the housing data reaction at the open, the auction and the minutes in the afternoon, and Palo Alto Networks after the bell, which today’s contracts will not see. A defined-risk structure such as a vertical spread fixes the worst case before entry. Size from that worst case, not from the premium collected, and remember that 1:00 to 2:30 p.m. is the busiest window of the day.
Desk rule for today: the earnings premium is gone; the rate premium is not.
Sources
- CNBC quotes: S&P 500 futures, Nasdaq 100 futures, Dow futures, NVIDIA (NVDA), VIX, 2-year, 10-year and 30-year Treasury yields, WTI crude.
- CNBC: Stock market today: live updates; Markets.
- Trading Economics: US economic calendar.
- Yahoo Finance: Earnings calendar.
Related reading
- Trading Calendars by Simon Hertz, available on Amazon.
- Trading Verticals by Simon Hertz, available on Amazon.
- Trading 0DTE Spreads by Simon Hertz, available on Amazon.
- All titles: Simon Hertz author page on Amazon.
This post is for education only. It is not investment advice or a recommendation to buy or sell any security or option. Options involve risk and are not suitable for all investors. Figures are from the sources listed and may be revised; check primary sources before relying on any number.