Nasdaq Plunges 5.52%, VIX Jumps to 28.18: Closing Notes for Thursday
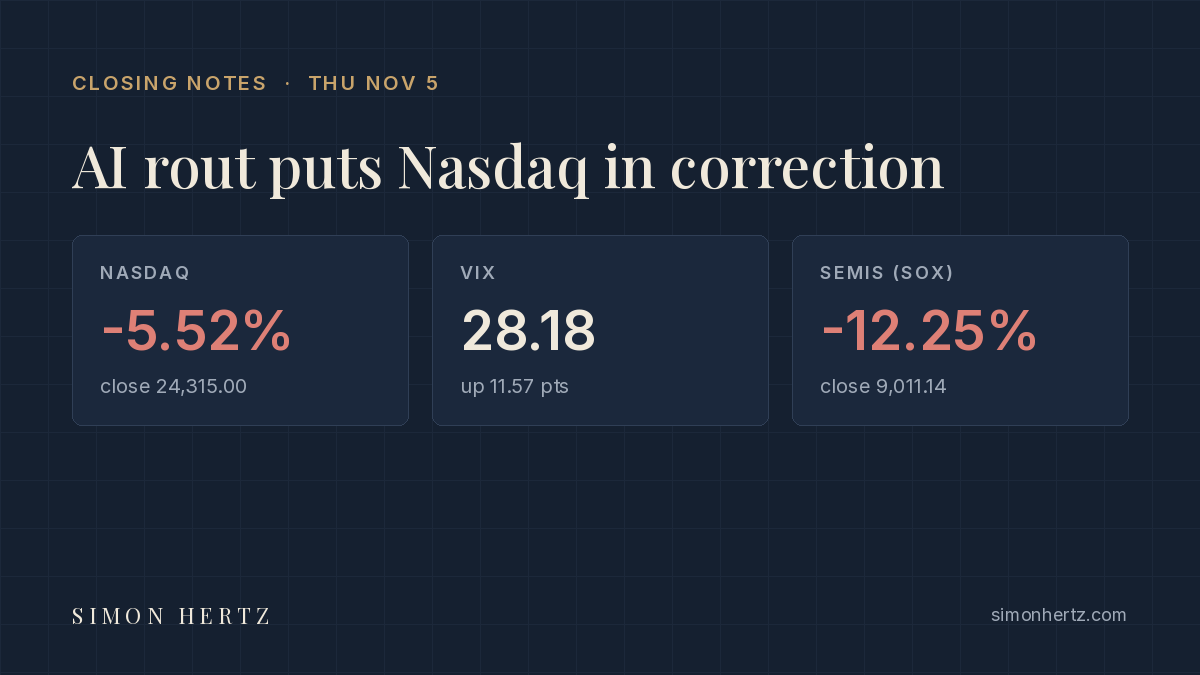
Thursday, November 5, 2026: Wednesday’s post-election rally reversed into the worst session for U.S. stocks since April 2025. The Nasdaq Composite fell 5.52% and closed in correction territory, the semiconductor index lost 12.25%, and the VIX rose about 70%. Bonds caught a bid while oil rose. After the bell, earnings split sharply, with Cloudflare and Airbnb up and Atlassian and Lyft down.
How the session closed
- Indexes. The Dow closed at 51,523.06, down 1,833.06 points or 3.44%. The S&P 500 fell 334.89 points, or 4.36%, to 7,353.73. The Nasdaq Composite lost 1,421.52 points, or 5.52%, to 24,315.00. The Russell 2000 fell 127.06 points, or 4.45%, to 2,729.89 (Yahoo Finance close quotes; AP and Fox Business agree on the moves).
- The milestones. The Nasdaq finished at least 10% below its October 6 record close, which is the usual definition of a correction (Fox Business, Yahoo Finance). AP had the S&P 500 and Dow on course for their worst day since April 2025, and a CNBC headline said the same of the Nasdaq.
- Why. The Democratic sweep raised concern about data center limits, power costs and a slower, more expensive AI buildout (AP, Fox Business). UBS, cited by Reuters via StockTitan, put about 30% of planned 2028 data center additions at risk. Investrade also pointed to Qualcomm’s phone-chip weakness, Micron pausing a $4.5 billion Taiwan plant, and reports of AI chips held up in Hong Kong. Nomura described hedge funds unwinding this year’s AI winners, and Vanda Research said retail investors were on track for their biggest selling day since March 2020 (both via Yahoo Finance).
- Chips. The PHLX Semiconductor index fell 12.25% to 9,011.14 (Yahoo Finance). Micron lost 17.46% to $656.39, AMD 17.26% to $404.40, Lumentum 18.68% to $509.70, Broadcom 10.43% to $291.53 and Nvidia 9.26% to $181.60 (CNBC). That leaves Nvidia negative for the year.
- Other big names. Dell fell 14.89% to $316.91. Meta lost 3.96% to $605.08, Microsoft 3.58% to $535.93, Alphabet Class A 2.20% to $282.57 and Apple 1.53% to $344.17 (CNBC). Tesla dropped 10.77% (Fox Business). AppLovin went the other way, up 31.04% after Wednesday’s results (StockTitan).
- Sectors and breadth. All 11 S&P sectors were lower in the final hour, and decliners led advancers by about 5 to 1 (Investrade).
- VIX. 28.18, up 11.57 points or 69.66%, last at 4:15 p.m. ET (CNBC; Yahoo Finance agrees). The day ran from 16.70 to 28.36, so it finished near the high.
- Yields. At 5:05 p.m. ET the 2-year was at 4.471%, down 0.11; the 10-year at 4.843%, down 0.049; and the 30-year at 5.259%, down 0.021 (CNBC, measured from its own prior close). Yahoo Finance had the 10-year at 4.837%. The short end led the drop.
- Fed pricing. CNBC, via StockTitan at 1:04 p.m. ET, had CME FedWatch odds of a December hike at 70.1%, down from 82.7% on Wednesday. This is a midday figure.
- Oil. WTI settled at $90.52, up $2.40, and Brent at $98.29, up $3.67 (Investrade; both changes match CNBC’s prior settles). Later quotes were higher: WTI $91.20 at 4:59 p.m. ET and Brent $99.18, up 4.82% (CNBC; Trading Economics has the same Brent price). Investrade tied the rise to doubts about an Iran deal.
- Data. Initial jobless claims were 189,000 against 196,000 expected, and continuing claims 1.718 million against 1.710 million. Third-quarter productivity rose 3.6% against 2.8% expected, and unit labor costs fell 0.7% against an expected 0.6% rise. Challenger job cuts were 43,994, from 43,281 in September (Trading Economics).
- Treasury bills. The 4-week auction stopped at 3.890%, from 3.910%, and the 8-week at 3.975%, from 4.020% (Trading Economics calendar).
After hours
Quotes below are CNBC’s, stamped 5:11 to 5:15 p.m. ET, compared with the 4:00 p.m. close. Results and consensus are from TipRanks headlines on the same CNBC pages unless noted.
- Cloudflare. Up 14.10% to $278.99, after falling 8.28% in the session. Third-quarter EPS of $0.38 beat $0.34, and fourth-quarter EPS guidance of $0.43 topped $0.38.
- Airbnb. Up 10.17% to $187.43. Revenue rose about 19% to $4.87 billion and EPS was $3.16 against $2.85 expected. Fourth-quarter revenue guidance of $3.22–$3.28 billion topped $3.16 billion, and the company raised its full-year growth outlook to the high teens and added a $12 billion buyback (Reuters via Investing.com; AskTraders).
- Atlassian. Down 15.76% to $154.40. Adjusted EPS of $1.65 beat $1.44, and second-quarter revenue guidance of $1.825–$1.835 billion compares with $1.82 billion expected. The company guided to fiscal-year revenue growth of 13.75%.
- Lyft. Down 7.90% to $16.43. It reported a third-quarter loss of $0.03 a share against a $0.20 profit expected, and guided fourth-quarter adjusted EBITDA to $188–$213 million.
- IREN. Up 4.94% to $18.92, after falling 16.95% in the session. Revenue of $228 million beat $221.71 million.
- IonQ. Up 3.10% to $27.25. A loss of $0.29 a share compares with an expected $0.79 loss, and the full-year revenue view rose to $505–$515 million against $455.11 million expected.
- Akamai. Down 1.08% to $77.00. Adjusted EPS of $1.77 beat $1.67, and the full-year range of $6.47–$6.68 straddles $6.64.
- Chips. Little bounce so far: Micron was up 1.70% to $667.52 and Nvidia up 0.22% to $182.00.
What it means for options traders
Realized blew through implied. Wednesday’s 16.61 VIX worked out to about 1.04% a day on the divide-by-16 shortcut. The S&P 500 moved 4.36%, more than four times that. Thursday’s 28.18 works out to about 1.76% a day, so the market has repriced sharply, yet that daily figure is still well below the move it just saw. The VIX is not at its extreme either: its 52-week high is 35.30, from March 9 (CNBC).
Yesterday’s lesson, reversed. Wednesday we noted how quickly premium came out once the election passed. One session later it was all back and more. A short-vol position sized on a 16 VIX was carrying far more risk than that number suggested. This is why defined-risk structures matter: on a vertical spread, the maximum loss is set when the trade goes on, not by the size of the gap.
Dispersion after the bell. Options implied about a 12.0% move for Atlassian and 17.6% for IREN (TipRanks headlines). Atlassian has so far moved 15.76%, past what was priced, on a quarter that beat on EPS. IREN’s after-hours move is far inside its implied range, but it follows a 16.95% regular-session drop that came before the report. On a day like this, part of any after-hours move may simply extend or reverse the session’s move, so the comparison with implied needs care.
What is left on the curve. Friday brings October payrolls (consensus 65,000 after 29,000, Trading Economics), and next Tuesday brings October CPI. In a sharp sell-off, the front of the volatility curve usually rises the most, which flattens the term structure or can invert it. That changes how calendar spreads price the gap between expirations.
Sources
- Yahoo Finance, Stock market today (close quotes, SOX, VIX, 10-year, Nomura, Vanda) and S&P 500 quote.
- CNBC quote pages, at about 5:15–5:25 p.m. ET: VIX, 2-year, 10-year, 30-year, WTI, Brent; stocks NVDA (with AMD, AVGO), MU, LITE, IONQ (with DELL, AAPL), ABNB (with MSFT, GOOGL, META), NET, TEAM, LYFT, IREN, AKAM.
- AP via KRMG, How major US stock indexes fared Thursday.
- Fox Business, Nasdaq tumbles 5% (closes, correction, causes, Tesla).
- StockTitan, Stock Market Today Live, November 5, 2026 (UBS via Reuters, Fed pricing, AppLovin).
- Investrade, Market Review (oil settlements, breadth, sectors in the final hour, stock news).
- Reuters via Investing.com, Airbnb and AskTraders, Airbnb.
- Trading Economics, calendar (data, bill auctions, payrolls consensus) and crude oil.
- Wednesday’s Closing Notes (prior closes, CPI date).
Related reading
- Trading Verticals by Simon Hertz, available on Amazon.
- Trading Calendars by Simon Hertz, available on Amazon.
- Trading 0DTE Spreads by Simon Hertz, available on Amazon.
- All titles: Simon Hertz author page on Amazon.
This post is for education only. It is not investment advice or a recommendation to buy or sell any security or option. Options involve risk and are not suitable for all investors. Figures are from the sources listed and may be revised; check primary sources before relying on any number.